
 If you have been catching the global matches at BC Place or watching the drama unfold with local fans, you have definitely seen it happen: a striker puts a spectacular, stadium-shaking ball into the back of the net, only for the linesman to raise the flag. The play goes to a Video Assistant Referee (VAR) review, and by a matter of inches, the goal is wiped off the board. OFFSIDE. In the high-stakes world of British Columbia real estate, first-time homebuyers face a remarkably similar trap. You find a place, get your mortgage approved, and prepare to score your dream home—only to realize a tiny rule violation has completely wiped out your First-Time Home Buyers' Property Transfer Tax (PTT) exemption, sticking you with an unexpected five-figure penalty right at the closing line. To keep your hard-earned cash safe, you need to understand the legal "lines" of the game. Let's break down the rules so your purchase stays completely onside. The Exemption Play: A Potential $8,000 Savings Normally, when you buy real estate in BC, the provincial government charges a Property Transfer Tax. The standard tax rate is calculated using a tiered system:
However, BC offers a massive financial assist to beginners. If you qualify, the First-Time Home Buyers' Program can grant you an exemption worth up to $8,000. But just like in soccer, if you cross the lines set by the Ministry of Finance, the whistle blows and the tax is back on your closing statement. Here are the three ways buyers accidentally wander into an offside position. 1. The Value Line: The $835,000 Threshold In soccer, the offside line is determined by the last defender. In BC real estate, the line is determined by the purchase price (or fair market value) of the home:
To qualify for the first-time buyer exemption, you must have an unblemished record.
What if you inherited a 10% share of a family condo abroad ten years ago? Are you automatically disqualified? This is where the exact wording of the law saves the play. The BC rule specifically penalizes you if you previously owned a stake in a property that was used as your principal residence (meaning a home where you actually resided and laid your head at night). If that foreign property or inherited condo slice was strictly used as a rental investment property, a vacant plot of land, or a commercial space, and you never occupied it as your main home, you are still legally considered a first-time home buyer in BC. But be warned. The Ministry of Finance runs its own strict VAR checks. If they audit your claim, the burden of proof is entirely on you. You must be ready to show a clear paper trail—like formal lease agreements, rental income statements, or tax filings—proving you never actually lived there. 3. The Post-Match Tactic: The 92-Day Occupancy Rule You can’t just score the goal and walk off the pitch; you have to play out the rest of the season. Once your notary registers the property in your name, the province monitors what you do next.
Let us act as the Linesman. Contact us to ensure your purchase stays safely onside.  In British Columbia, a Notary Public plays an important role in helping individuals and families handle key legal matters—especially those that require reliability, clarity, and proper documentation. While notaries are not lawyers, they are highly trained legal professionals with a defined scope of practice focused on non-contentious matters.
What Can a BC Notary Do? A BC Notary Public is authorized through the Society of Notaries Public of British Columbia to provide a range of legal services, including:
What Is Outside a Notary’s Scope? BC Notaries generally do not handle contentious legal matters, such as disputes, litigation, or complex family law issues. In those situations, clients are typically referred to a lawyer. Why This Matters to Clients The scope of a BC Notary’s practice is designed to provide accessible and efficient legal services for everyday needs—particularly in real estate and estate planning. For many transactions, working with a Notary can be a cost-effective and streamlined option. Let us handle the paperwork for your next big milestone. Click here to reach out today to see how we can help.  Buying your first home can feel overwhelming, especially with rising real estate prices in BC. The First Home Savings Account (FHSA) is a new tool designed to help first-time homebuyers save more efficiently while enjoying tax benefits.
What is the FHSA? The FHSA is a registered account that combines the benefits of an RRSP and a TFSA. Canadians can contribute up to $8,000 per year (with a lifetime limit of $40,000) toward their first home. Contributions are tax-deductible, and withdrawals for a qualifying home purchase are tax-free. Who Can Open an FHSA?
Qualifying Withdrawals To use your FHSA funds tax-free, withdrawals must meet certain criteria:
Why the FHSA is Useful
Check out the official link from the Government of Canada or speak to your bank for more details.  It’s official! The GST Rebate for First-Time Home Buyers has received Royal Assent, and the CRA is now processing claims that could save you up to $50,000! Canada’s new government has eliminated the GST on new homes up to $1 million and reduced it for homes up to $1.5 million for agreements signed between March 20, 2025, and 2031. To get your rebate as fast as possible, simply log into your MyCRA account to apply online; while we are happy to assist with the paperwork, please note that manual applications will take slightly longer to process.
Check out our link here and the official site from Government of Canada for more information about this program, including how to apply for the rebate. While a drop in BC Assessment values might seem like an automatic tax relief for homeowners, the reality is more nuanced. For the 2026 property tax year, many homes in the Lower Mainland saw assessed values decline by up to 10% due to a softening real estate market.
However, municipal governments still set property tax rates based on the total revenue needed to fund local services. This often results in a “revenue-neutral” adjustment, meaning your taxes may not decrease proportionally with your assessment. Why Your Property Taxes Might Still Rise It’s important to understand that an increase or decrease in your property’s assessed value does not automatically determine your tax bill. Taxes are calculated relative to the average change in property values across your municipality. For example: If your home’s value fell by only 2%, but your neighbors’ properties fell by an average of 8%, your share of the municipal tax pool has effectively increased. In this scenario, even with a lower assessment, you could see a higher property tax bill because your property now represents a larger relative portion of the community’s total taxable value. Home Owner Grant Threshold Adjustments The provincial government has adjusted the Home Owner Grant (HOG) eligibility to reflect these market changes. For 2026, the maximum property value for the full HOG was lowered from $2.175 million to $2.075 million. This $100,000 reduction ensures the grant continues to target the same proportion of homeowners as in previous years. However, homeowners whose properties declined less than the provincial average may see a partial or full loss of the grant. The adjustment highlights the importance of checking your eligibility early to avoid surprises on your property tax bill. Click here for more details.  British Columbia’s Property Tax Deferment Program allows eligible homeowners—such as seniors, persons with disabilities, and some families with children—to postpone paying their annual property taxes. Instead, the provincial government pays the taxes on the homeowner’s behalf and registers the amount as a loan against the property, which is typically repaid when the home is sold or transferred. Interest is charged on the deferred amount starting from the tax due date (or the application date, whichever is later), along with certain administrative fees. Historically, interest has been calculated using simple interest (not compounded) at a rate up to 2% below the bank’s prime rate, making the program a relatively inexpensive financing option.
What Is Changing in 2026? Beginning with 2026 property taxes, the province will change how interest is calculated on newly deferred taxes:
Refer to the official Government of British Columbia page: Property Tax Deferment Interest and Fees. One of the most common questions I've been asked most about Power of Attorney (POA) is, what if I don't have a POA and I become incapable of making decisions for myself? My answer is - you're going to create a lot of trouble for your family or whoever needs to help you to manage your affairs. When an adult needs help managing their affairs because of mental incapability due to an illness, accident, disability or diseases associated with aging, their judgment may be impaired in some way. They may forget to pay bills or put money away and forget where it is. The adult may also be confused about banking, investments, property, and personal belongings. However, they may have planned ahead and authorized someone else to make decisions and managing their financial and legal affairs through an enduring power of attorney. But what if the adult does not have a POA? 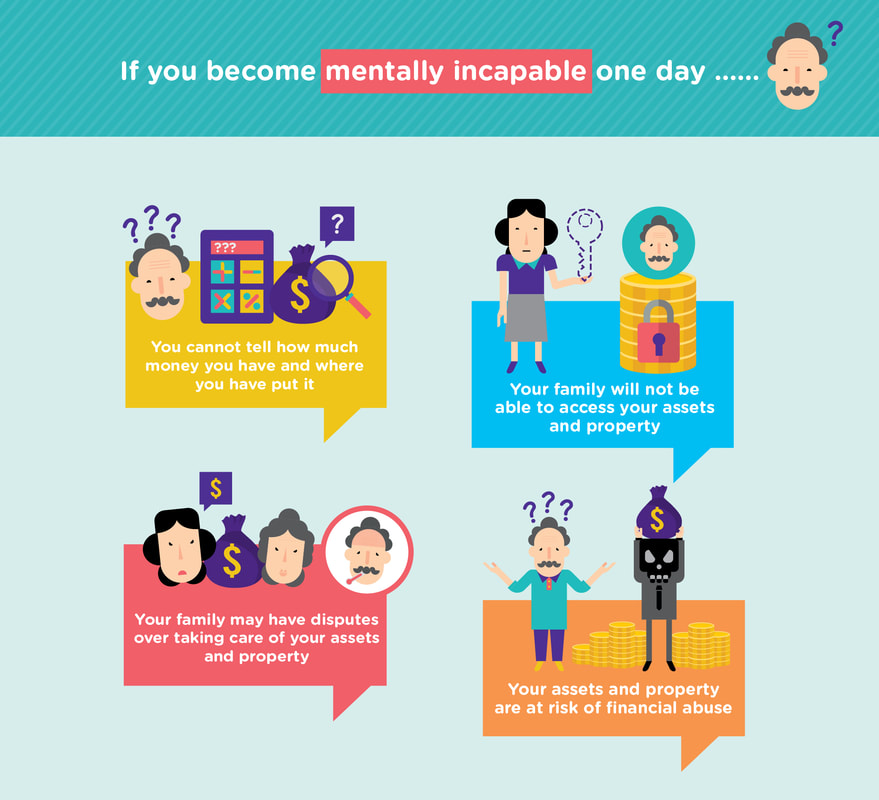 British Columbia has been able to develop one of the best land survey and title registration systems in the world. British Columbia, including the colonies before the province came into existence, has always maintained a system for recording ownership and interests in private land. For a short while, the colonies maintained Deeds Registries. However, a Deeds Registry results in a complicated, unreliable system for recording interests in land. In order to gain an opinion on ownership of interests in land, an unbroken chain of documentary evidence over long periods of time or possibly from the original granting of the land from the Crown is required. If any one of those documents was not properly executed, or if all documents in the chain cannot be obtained, then a shadow of doubt is cast upon the claim of ownership.  The British Columbia government has launched the Condo and Strata Assignment Integrity Register (CSAIR) to crack down on tax evasion and improve fairness and transparency in B.C.’s real estate market. It is widely acknowledged that the practice of pre-sale flipping has been lacking of transparency. It is unknown exactly how many assignment flips occur each year. This new register will require developers to add or file assignments on new developments. This information will be gathered securely by the developer. The information that must be reported includes identity and citizenship of all parties to the assignment.  In many instances, banks and financial institutions require the borrowers to obtain a title insurance. However, this policy only protects the bank’s interest and insures against financial loss in the event of a defects in title to the property. In British Columbia, title defects rarely happen. When a land title is transferred, the new owner can be assured that his/her title is “indefeasible” (meaning the title transfer cannot be defeated, revoked, or made void) under the Torrens system, as long as the owner acquires the interest in good faith and for value consideration.  |
 RSS Feed
Talk to us today!
Hours of OperationMonday 9:00am to 5:30pm
Tuesday 9:00am to 5:30pm Wednesday 9:00am to 5:30pm Thursday 9:00am to 5:30pm Friday 9:00am to 5:30pm Saturday Closed Sunday Closed |
Call and Fax
|
Addresss
|
Google Us

|

Members of the Society of Notaries of British Columbia
|
Copyright © 2024 Jerome Tsang Notary Corporation | dba Jerome Tsang and Lucy Kim Notaries Public| Notaries of British Columbia | Sitemap